About of Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme
Looking for the latest information on Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme? We've compiled comprehensive data, records, and insights about Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme.
Core Information
Explore the key sources for Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme.
History
Stay updated on Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme's latest milestones.
Ornstein-Uhlenbeck process | Simulation in Python
Code Review: Using Euler-Maruyama method to solve Ornstein-Uhlenbeck equation (SDE)
Método de Euler-Maruyama para resolver ecuaciones diferenciales estocásticas
Euler method (Python)
Monika Eisenmann – Backward Euler-Maruyama method for SDEs with multi-valued drift coefficient
Stochastic Differential Equations for the Deterioration Processes of Engineering Systems
Solving stochastic differential equations step by step; using Ito formula and Taylor rules
Keynote. Simulating Stochastic Dynamical Systems With Runge-Kutta Schemes | A Rößler | SciMLCon 2022
Detailed Analysis
Data is compiled from public records and verified media reports.
Last Updated: September 27, 2026
Summary
For 2026, Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme remains one of the most talked-about information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
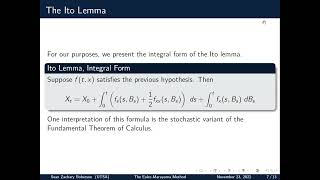
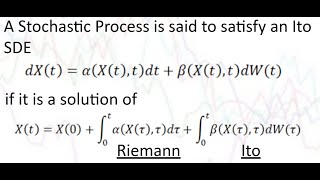
We're looking at the structural breakdown of Recorded for an assignment for the course AIM 5113 at UTSA. This video describes (quite briefly) the Procedure for simulating the Ornstein-Uhlenbeck process in amzn.to/4aLHbLD You're literally one away from a better setup — grab it now! As an Amazon Associate I earn ... This talk is part of MCQMC 2020, the 14th International Conference in Monte Carlo & Quasi-Monte Carlo Methods in Scientific ... Submission for the 2019 CERRA Student Recognition Award. To solve the geometric Brownian motion SDE which is assumed in the Black-Scholes model. This talk was part of SciMLCon 2022! For more information, scimlcon.org/2022/. For more information on the ...
Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme.pdf
What is the most accurate information about Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme?
Our platform aggregates the most comprehensive and up-to-date insights, ensuring you get relevant details about Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme.
Why is Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme trending right now?
Interest in Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme has surged recently as more people seek reliable resources, related media, and detailed analysis.
Where can I find related media and updates for Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme?
You can explore extensive galleries, video summaries, and related content directly on this page.
How often is the content about Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme updated?
We regularly update our database with the latest information, media, and analysis related to Stochastic Differential Equation Theory Simulation Code In Fortran Python Euler Maruyama Scheme.