Looking for the latest information on Ma 1 Processes? We've gathered comprehensive data, records, and insights about Ma 1 Processes.
Important Facts
Explore the main sources for Ma 1 Processes.
Recent Updates
Stay updated on Ma 1 Processes's newest achievements.
MA Process
MA(1) Process
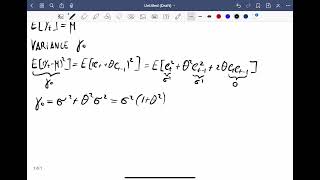
MA(1) Moving Average Process: Mean Autocovariances and ACF
Invertibility - converting an MA(1) to an AR(infinite) process
Time Series Talk : ARMA Model
Time Series Talk : Moving Average Model
Time Series Talk : Autoregressive Model
Properties of MA Part 1
Autoregressive vs Moving Average Order One processes - part 1
Autoregressive Order one process introduction and example
What are Autoregressive (AR) Models
Deep Dive
Data is compiled from public records and verified media reports.
Last Updated: September 27, 2026
Final Thoughts
For 2026, Ma 1 Processes remains one of the most searched-for information profiles. Check back for the newest reports.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
This video provides an introduction to Moving Average of Order One So this means both this expectation and this expectation are zero and we in fact do confirm that the mean of an Representation, Mean, Variance, ACF of moving average The second piece to an ARIMA model is a moving average ( ... 1 or i can just simply write theta because i have just one term theta dt minus 1 okay so that's the uh that's the uh I show how to compute the moments of a This video explains what is meant by 'invertibility' in econometrics, as the condition allowing conversion of an The Autoregressive Moving Average (ARMA) model in time series analysis. A gentle intro to the Moving Average model in Time Series Analysis. ... deal with the properties of m a process in previous lecture we explained the mathematical form we can express a Time to start talking about some of the most popular models in time series - ARIMA models. First things first, let's look at the AR ...