Looking for the latest information on Ar 1 Process Properties? We've gathered comprehensive data, records, and insights about Ar 1 Process Properties.
Core Information
Explore the key sources for Ar 1 Process Properties.
History
Stay updated on Ar 1 Process Properties's newest achievements.
Properties of an AR(1) Model
What are Autoregressive (AR) Models
AR(1) Process: Mean, Variance, Autocovariance and Autocorrelation function.
Stationarity of MA(inf) and AR(1) process
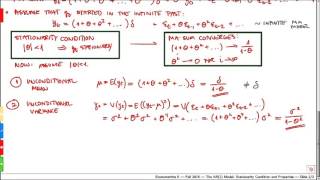
The AR(1) Model - Stationarity Condition and Properties Given Stationarity
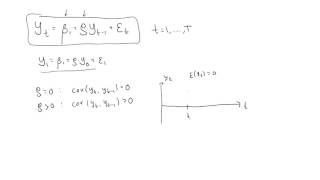
The AR(1) process
Time Series Talk : Autoregressive Model
ARproperties
8.2 Time Series - Autoregressions - AR1 model
1 3 AR1 wtih R
AR(1) Process Estimation
Expert Insights
Data is compiled from public records and verified media reports.
Last Updated: September 30, 2026
Conclusion
For 2026, Ar 1 Process Properties remains one of the most talked-about information profiles. Check back for the latest updates.
Disclaimer: Disclaimer: All information is compiled from publicly available data, media reports, and analysis. Actual details may vary.
Summary
In this lecture we will be continuing our treatment of autoregressive one This video provides an introduction to Autoregressive Order One We consider a first-order autoregressive This is the video associated with QR code QR5.2 in Chapter 5 of Time Series for Data Science: Analysis and Forecasting by ... Time to start talking about some of the most popular models in time series - ARIMA models. First things first, let's look at the Full derivation of Mean, Variance, Autocovariance and Autocorrelation function of an Autoregressive Here we establish the Stationarity conditions of MA(inf) and We present the stationarity condition for the Up until now we have talked about autocorrelations which means that the quantedu.wordpress.com/2015/07/06/autoregressive-one/ ...